Utility stocks fell 10% this past year even as their profits rose 15%
In the year power became the scarcest input in the AI buildout, investors paid less for the companies that sell it. The utilities fund's top holdings fell 9.8% while their net income rose 15%, so the trailing P/E fell from 27x to 21x. The 10-year Treasury yield rising from about 4.0% to 5.1% weighed more than demand: the market is still pricing utilities as rate-sensitive income stocks, not as AI winners.
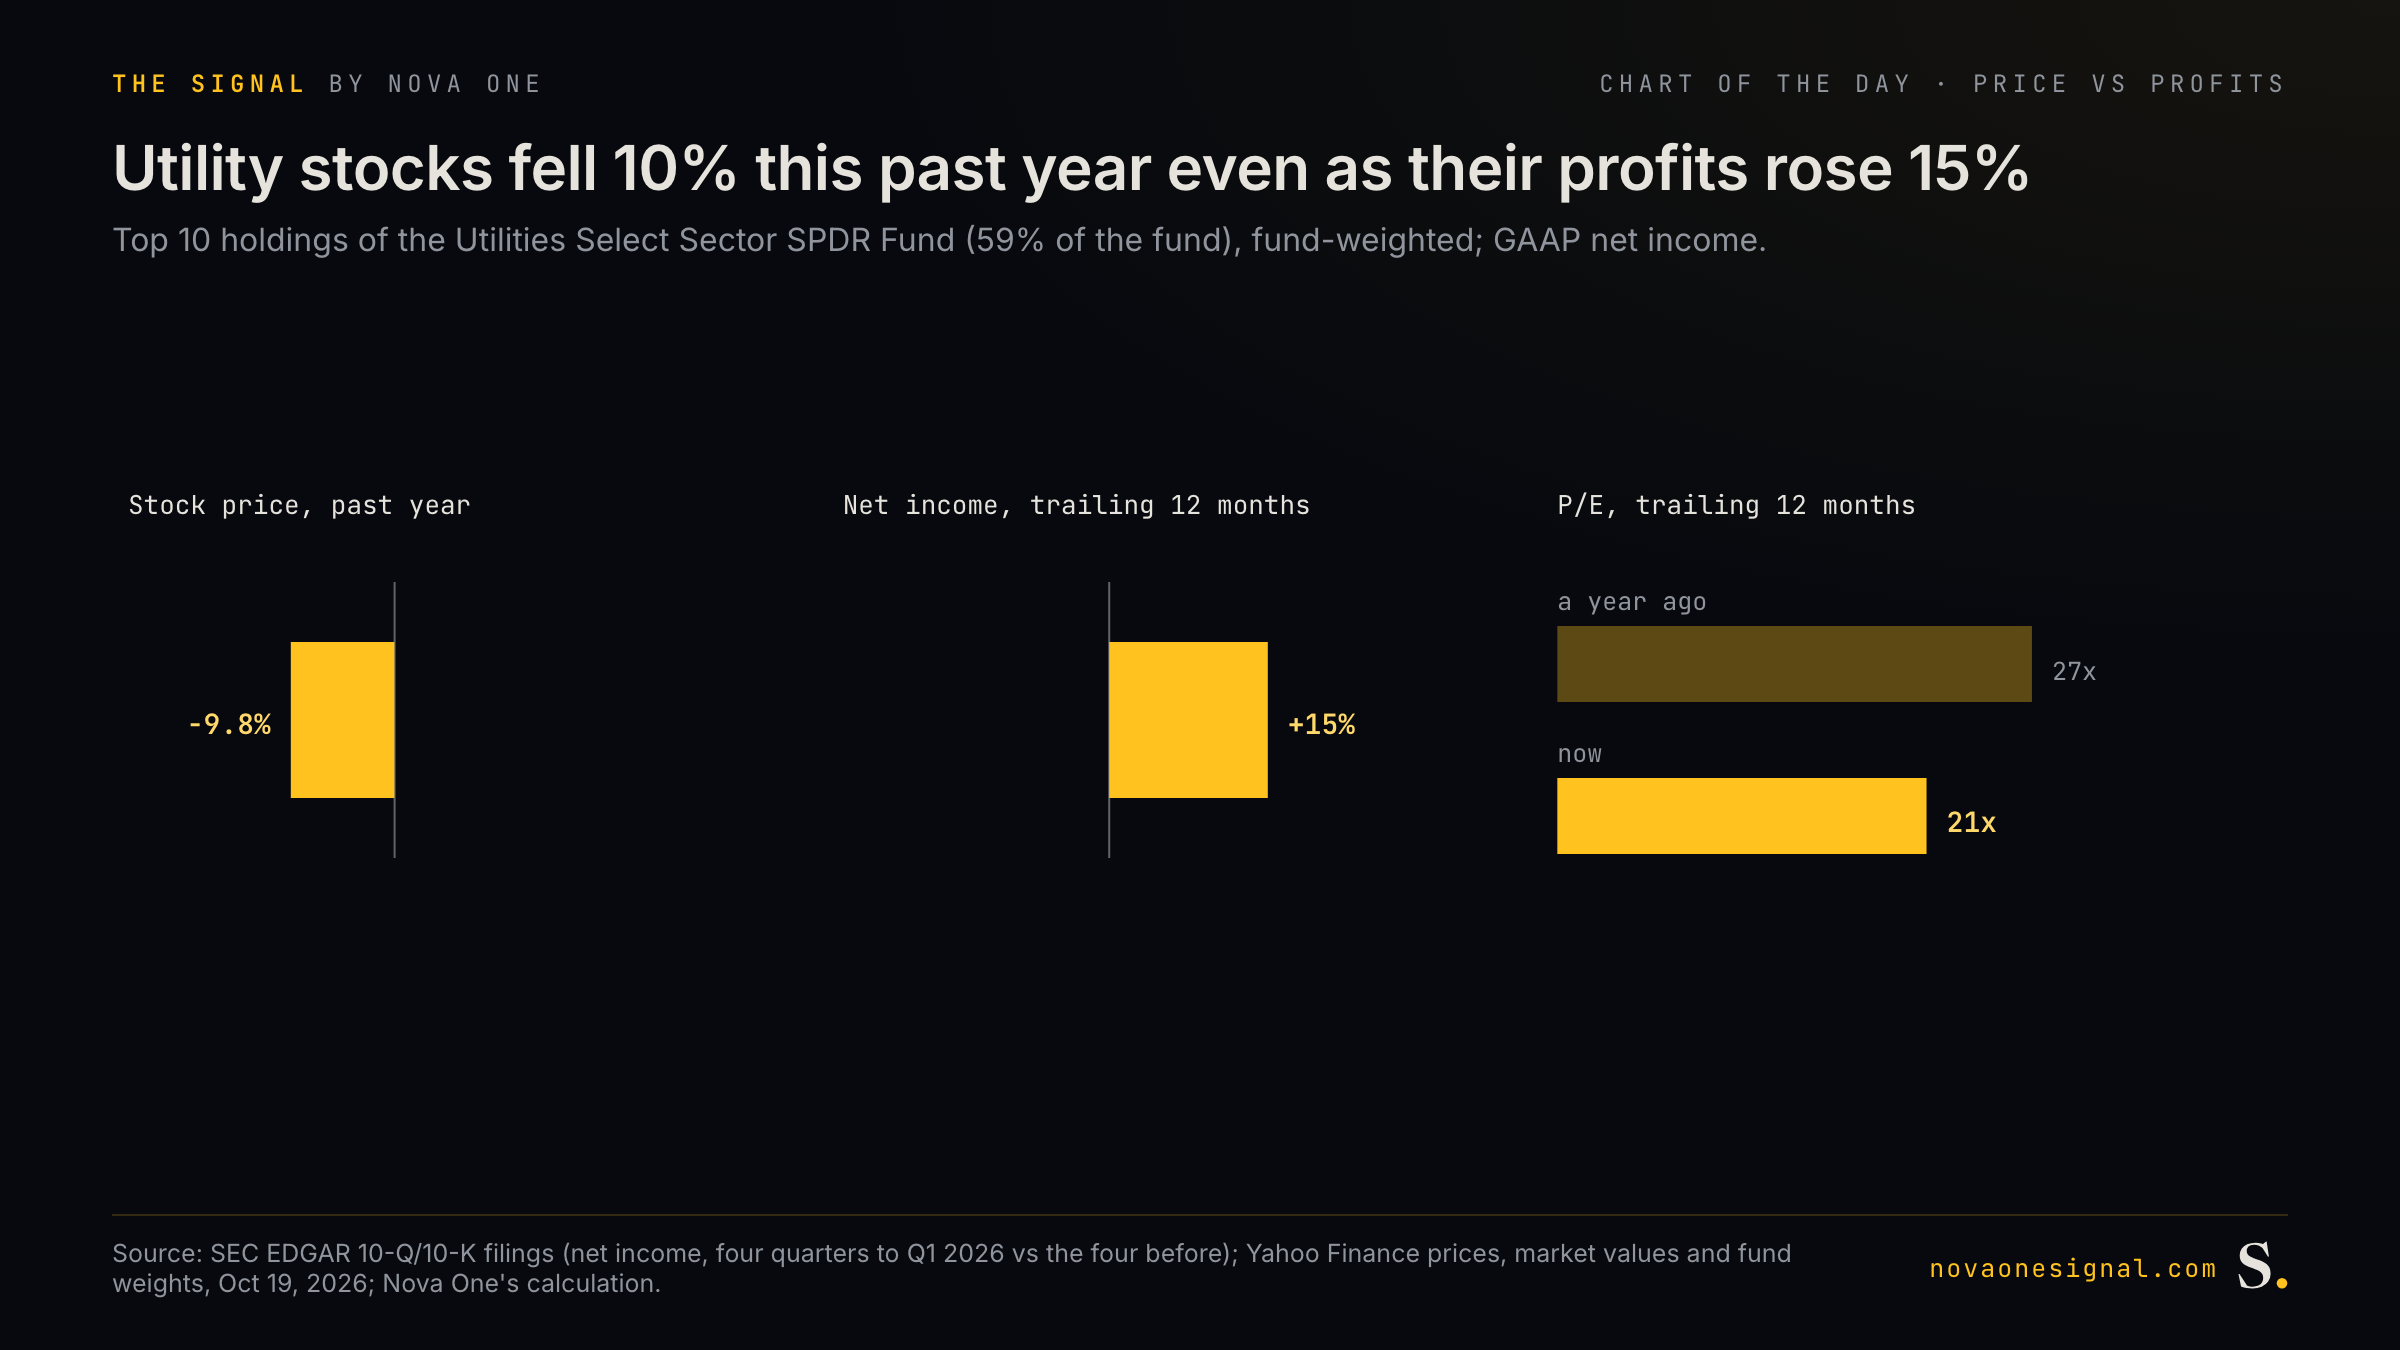
Three panels: the stock price change over the past year, the change in net income over the trailing 12 months, and the price-to-earnings ratio a year ago and now. The utilities are measured through the ten largest holdings of the sector fund, weighted as in the fund.
It separates the AI power story from the stocks that are supposed to express it. If rates ease, the gap between rising profits and falling multiples is where the move would come from.
The common view: the AI power shortage makes utilities a winner.
The Signal deskTop 10 holdings of the Utilities Select Sector SPDR Fund (59% of the fund), fund-weighted: price down 9.8% over the past year; GAAP net income up 15% (four quarters to Q1 2026 vs the four before); trailing P/E from 27x to 21x. NextEra Energy supplied 57% of the profit increase.
Demand is showing up in the earnings, and the market is not paying for it. Until rates turn, the shortage helps the income statement more than the stock.
Get The Signal by email
Two letters a week: a Mid-Week Check-In on Wednesdays and a Week in Review on Saturdays.
We use your address only to send The Signal. Unsubscribe any time. Privacy
Source: SEC EDGAR 10-Q/10-K filings (net income, four quarters to Q1 2026 vs the four before); Yahoo Finance prices, market values and fund weights, Oct 19, 2026; Nova One's calculation. Every number on the chart is computed from the source data in the same run that drew it. The Signal is research, not investment advice. How we work · Disclosures